
Nevada · Over $6 Million
Nevada Multifamily Loans
Select Commercial arranges Nevada multifamily loans, with rates as low as 6.14%, up to 80% LTV and non-recourse agency options. We compare Fannie Mae, Freddie Mac, FHA/HUD and CMBS. For loans under $6 million, see Nevada apartment loans. See current rates on every loan type we offer.
Get a Free QuoteFinancing Options in Nevada
Nevada apartment, multifamily and commercial properties each have dedicated financing. Pick the page that matches your property:
Financing more of the state? See Nevada apartment loans and Nevada commercial mortgages.
Financing in another state? Explore our apartment loans, multifamily loans and commercial mortgages nationwide.
Nevada Multifamily Loan Rates
Rates updated as of October 22, 2026
| Loan Type | Rate* | Max LTV |
|---|---|---|
| 5 Year Fixed | 6.14% | Up to 80% |
| 7 Year Fixed | 6.17% | Up to 80% |
| 10 Year Fixed | 6.21% | Up to 80% |
- Streamlined underwriting for institutional multifamily
- Cash-out refinances are acceptable
- Interest-only and non-recourse options
- Minimum 1.25x debt-service-coverage ratio
Nevada Apartment Loans
For smaller apartment building loans, under $6 million
Rates last updated October 22, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
Nevada Apartment Building Loans
Not every Nevada apartment property is over $6 million, and we finance smaller buildings too. For 5+ unit Nevada apartment properties from $1,500,000 to $6 million, see our Nevada apartment loans page for Fannie Mae Small Loan, Freddie Mac SBL, bank and credit union options.
Compare Nevada Large-Balance Programs
As a broker we place your large-balance Nevada multifamily loan with the right capital source. Typical starting points for properties over $6 million:
| Program | Typical rate* | Max leverage | Best for |
|---|---|---|---|
| Fannie Mae DUS | 6.14% | Up to 80% | Non-recourse, fixed to 30 yrs |
| Freddie Mac | 6.17% | Up to 80% | Non-recourse large-balance |
| FHA / HUD | 6.74% | Up to 85% | Highest leverage, 35-yr amortization |
| CMBS / conduit | 7.03% | Up to 75% | Non-recourse, flexible underwriting |
Most large-balance lenders look for a debt-service-coverage ratio (DSCR) of at least 1.25x. For properties under $6 million, see our Nevada apartment loans.
Rates last updated October 22, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
2026 Nevada Multifamily Investment and Lending Outlook
Nevada contains the tightest and one of the softest apartment markets in the western United States, about 450 miles apart.
In Reno and Sparks, Johnson Perkins Griffin’s second-quarter 2026 survey of 122 projects and 32,027 units, limited to stabilized market-rate complexes of 80 or more units, reported overall average rent of $1,850 and vacancy of 1.87%. Rent rose $52, or 2.89%, quarter over quarter, and the share of projects offering concessions fell from 30.33% to 20.49% in a single quarter. Submarket vacancy ranged from 1.44% in East Sparks to 3.27% in the downtown urban core, with 1,654 units under construction. Note that the rent and vacancy changes above are quarterly, not annual, and should not be annualized.
Las Vegas is the other story, and the published figures diverge enough that the divergence is itself the useful fact. Yardi Matrix reported average asking rent of $1,478 through June 2026, down 0.9% year over year, with stabilized occupancy of 92.6%, down 80 basis points. MMG Real Estate Advisors reported average rent of $1,380, down 4.6% year over year, at 90.5% occupancy. Those sit 370 basis points apart on rent growth.
The gap is almost certainly asking rent against effective rent, and in Las Vegas that gap is concessions. Your lender will underwrite the lower number. Debt service coverage is calculated on collected rent net of concessions, not on a gross rent roll, so a Las Vegas borrower should expect sizing off something closer to the effective figure. MMG’s pipeline count as of August 2026 explains why concessions persist: 4,336 units under construction, 4,711 units in pre-lease or lease-up, and 3,855 planned, totaling 12,902 units across 41 locations.
Neither market has a published cap rate, price per unit or transaction volume figure from a source we would quote. Ask for property-specific comparable sales.
Nevada Ties Your Property Tax Cap to Your Rents, and the Affidavit Is Due June 15
Nevada is the only state in this group that wires a rent ceiling directly into the property tax escalator. If you push rents past a specific threshold, your tax cap can nearly triple. No other state does this, and most borrowers have never heard of it.
The structure. The partial abatement created by Assembly Bill 489 of 2005, at NRS 361.471 through 361.4735 with regulations at NAC 361.606 through 361.609, caps the annual increase in a property tax bill. An owner-occupied primary residence is capped at 3%. A qualifying residential rental property is also capped at 3%, provided all units are rented at or below the HUD-determined rent level for the county and an annual affidavit is on file. Everything else, including any apartment that does not qualify, falls under a variable cap recomputed every year and not to exceed 8%.
Five consequences, and they are all operational rather than credit.
The affidavit is due on or before June 15, every year. Miss it and the parcel drops from the 3% cap to the up-to-8% cap. That is not a one-year problem. It permanently resets the base from which every future cap is measured. On a property where taxes run 15% to 25% of gross revenue, that is a direct coverage event. Put the affidavit on the annual compliance calendar beside the insurance renewal, and consider making it an express covenant.
The cap and the rent roll are coupled. The 3% cap is conditioned on rents staying at or below the HUD threshold for the county. Raise rents above it and you forfeit the cap. So a Nevada borrower relying on the 3% cap has to weigh incremental rent revenue against a step-up in the tax escalator, and the arithmetic argues against aggressive rent trending on such an asset. Confirm which HUD rent table applies to your county before you test your rent roll against it, because the standard is described more than one way.
Closing resets the affidavit. A transfer of ownership triggers a new affidavit mailed to the new owner. A buyer who does not complete it loses the 3% cap. This belongs on the closing checklist and as a post-closing covenant.
New construction and change of use are uncapped. Under NAC 361.6085 the cap is eliminated for new construction, a change in use classification, or property that previously escaped taxation. A newly delivered Nevada apartment gets no cap protection in its first year on the roll. On a construction-to-permanent or lease-up loan, the stabilized tax assumption has to be the fully assessed, uncapped figure.
The 8% figure is a ceiling, not a floor. The cap for non-qualifying property is recomputed annually and can sit well below 8%. It offers less protection in a boom than the headline implies, and less than you would want in a downturn.
Two Nevada items that cut the other way, in the borrower’s favor and against the usual pitch.
There is no tax on recording a mortgage. NRS 375.010(1)(b) provides that the real property transfer tax does not apply to a deed of trust or common-law mortgage instrument encumbering real property. Only title transfers are taxed. In Clark County the combined transfer tax runs $2.55 per $500, or 0.51%, on the deed, which is about $127,500 on a $25,000,000 sale, and nothing on the loan. Compare Maryland, where a $20 million loan can carry $230,000 in recordation tax by itself.
Nevada is not tax-free at the entity level. The absence of a state income tax is the standard reason people structure into Nevada, but the Commerce Tax at NRS 363C applies to a business entity whose Nevada gross revenue in a taxable year exceeds $4,000,000, at a rate of 0.25% for the real estate and rental and leasing category. Returns are due on or before the 45th day after the taxable year ends on June 30. Because it is assessed on gross rather than net revenue, it does not disappear in a weak year, and it belongs as an operating expense in underwritten net operating income rather than as an owner-level item. A large Nevada apartment portfolio crosses that threshold easily, and the affiliated-group rules limit how far revenue can be split across entities to stay beneath it.
2026 Nevada Multifamily Metro Snapshots
A look at the Nevada metros we most actively finance, with 2026 market indicators and the local supply and demand picture:
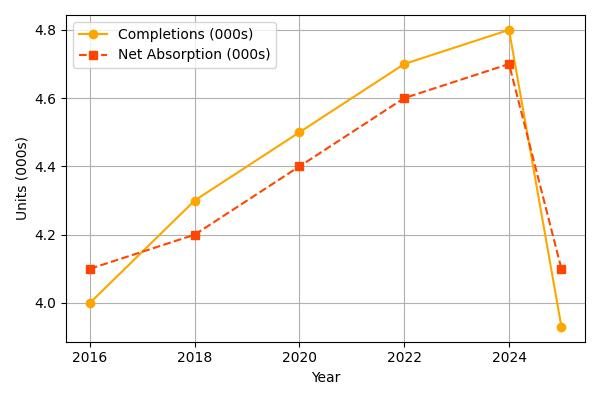
- Employment: Employment is expected to post slight growth in 2026, with the workforce projected to expand by about 3,000 jobs (roughly +0.3%).
- Construction: A clear pullback in deliveries is expected, with about 1,300 units of new supply and total inventory growth projected at roughly 0.5%.
- Vacancy: Vacancy projected to improve by about 50 basis points to roughly 5.0%.
Nevada Multifamily Loan Programs
As a broker, we compare every large-balance program to find your best fit:
Recent Multifamily Loan Closings
A sample of apartment and multifamily loans we have arranged for investors nationwide.





Other Property & Loan Types We Finance in Nevada
As a full-service commercial mortgage broker, we arrange Nevada financing across every major property and loan type:
We consider commercial loan requests of all sizes, beginning at $1,500,000.
What Our Clients Say
“As a real estate attorney, I trust that Select Commercial will deliver commercial mortgages in a timely manner. My clients are always handled professionally, and the rates and terms are excellent. I heartily recommend them.”
David S. · New York City“I spoke to several commercial lenders before finding Select Commercial. They got me a lower rate and their service was exceptional. If you need a multifamily loan, you need to talk to Stephen.”
Nathan B. · Philadelphia, PA“Select Commercial was very helpful with my multifamily mortgage. Stephen went over several options and we came up with the best lender to meet my needs. I got the funds and also lowered my payments.”
Gary M. · Portland, OR“Select Commercial offered 100% financing for my medical practice when my bank would have required 20% down. They delivered something my bank could not, and handled everything professionally.”
John C. · Boston, MAGet Your Nevada Multifamily Loan Quote
No cost, no obligation. Written answers within 48 hours on Nevada multifamily loans over $6,000,000.
- No application or processing fees
- Written answers within 48 hours
- For 5+ unit and commercial properties, $1.5M and up