
North Carolina · Over $6 Million
North Carolina Multifamily Loans
Select Commercial arranges North Carolina multifamily loans, with rates as low as 6.14%, up to 80% LTV and non-recourse agency options. We compare Fannie Mae, Freddie Mac, FHA/HUD and CMBS. For loans under $6 million, see North Carolina apartment loans. See current rates on every loan type we offer.
Get a Free QuoteFinancing Options in North Carolina
North Carolina apartment, multifamily and commercial properties each have dedicated financing. Pick the page that matches your property:
Financing more of the state? See North Carolina apartment loans and North Carolina commercial mortgages.
Financing in another state? Explore our apartment loans, multifamily loans and commercial mortgages nationwide.
North Carolina Multifamily Loan Rates
Rates updated as of October 23, 2026
| Loan Type | Rate* | Max LTV |
|---|---|---|
| 5 Year Fixed | 6.14% | Up to 80% |
| 7 Year Fixed | 6.17% | Up to 80% |
| 10 Year Fixed | 6.21% | Up to 80% |
- Streamlined underwriting for institutional multifamily
- Cash-out refinances are acceptable
- Interest-only and non-recourse options
- Minimum 1.25x debt-service-coverage ratio
North Carolina Apartment Loans
For smaller apartment building loans, under $6 million
Rates last updated October 23, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
North Carolina Apartment Building Loans
Not every North Carolina apartment property is over $6 million, and we finance smaller buildings too. For 5+ unit North Carolina apartment properties from $1,500,000 to $6 million, see our North Carolina apartment loans page for Fannie Mae Small Loan, Freddie Mac SBL, bank and credit union options.
Compare North Carolina Large-Balance Programs
As a broker we place your large-balance North Carolina multifamily loan with the right capital source. Typical starting points for properties over $6 million:
| Program | Typical rate* | Max leverage | Best for |
|---|---|---|---|
| Fannie Mae DUS | 6.14% | Up to 80% | Non-recourse, fixed to 30 yrs |
| Freddie Mac | 6.17% | Up to 80% | Non-recourse large-balance |
| FHA / HUD | 6.74% | Up to 85% | Highest leverage, 35-yr amortization |
| CMBS / conduit | 7.03% | Up to 75% | Non-recourse, flexible underwriting |
Most large-balance lenders look for a debt-service-coverage ratio (DSCR) of at least 1.25x. For properties under $6 million, see our North Carolina apartment loans.
Rates last updated October 23, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
2026 North Carolina Multifamily Investment and Lending Outlook
Charlotte is absorbing units at record rates and its headline vacancy is still over 12%. Both facts are true, and knowing which number your lender uses is worth real money.
Cushman & Wakefield reported Charlotte whole-market vacancy of 12.3% in the second quarter of 2026 across a 245,006-unit inventory, with asking rent at $1,635, quarterly net absorption of 5,036 units and 16,508 units under construction. Yardi Matrix, measuring the same market at roughly the same time, reported occupancy of 93.6% in stabilized properties, which is stabilized vacancy of about 6.4%.
That six-point gap is not a disagreement. It is the lease-up pipeline. Charlotte completed 6,596 units in the first half of 2026, equal to 2.6% of existing stock and 170 basis points above the national completion rate, and newly delivered units in initial lease-up are counted as vacant in a whole-market figure. A stabilized Charlotte property sits in a 6% vacancy market. A property delivering next quarter competes against everything else leasing up at the same time. Make sure the comparable set in your appraisal matches which one you own.
Charlotte transaction volume ran about $552 million through June 2026, down 11.3% from the prior-year period, at roughly $177,000 per unit, with asking rent down 1.4% year over year. Employment grew 0.9% through April 2026, adding about 14,900 net jobs.
Raleigh is further through its cycle. Cushman & Wakefield put whole-market vacancy at 9.5% across 134,159 units with 7,342 units under construction, and Yardi reported 93.1% stabilized occupancy. Northmarq reported second-quarter 2026 net absorption of roughly 2,600 units, more than double deliveries, with Raleigh absorbing more than 5% of its stock over twelve months and Durham 3.8%, and units under construction down 21% year over year. Nearly 95% of recorded transactions occurred on the Raleigh side. Construction starts fell 47% from the prior-year period.
First Citizens BancShares, headquartered in Raleigh, held $151.03 billion of loans and leases at June 30, 2026, which gives North Carolina borrowers unusually deep in-state bank capacity alongside the agencies.
Buying a North Carolina Property Does Not Reassess It, and That Is the Whole Game
North Carolina works the opposite way from most states, and the difference is worth understanding precisely because it turns tax underwriting from a formula into a calendar.
A sale does not trigger a reassessment here. Under N.C.G.S. § 105-286, each county must reappraise all real property as of January 1 of its scheduled year and every eighth year thereafter. Between reappraisals, § 105-287(b) affirmatively bars the assessor from increasing or decreasing appraised value to recognize a change in value caused by inflation, deflation, or other economic changes affecting the county in general, by normal, physical depreciation of improvements, or by listed minor betterments such as repainting and landscaping. A market-clearing trade is an economic change affecting the county in general. It is not a permitted trigger.
Values hold absent a structural addition or a change in legal use. Then, when the reappraisal arrives, § 105-283 requires all property to be appraised at true value in money, defined as market value, that is, the price estimated in terms of money at which the property would change hands between a willing and financially able buyer and a willing seller.
So the tax line is flat from closing until a known January 1, and then it steps to market in a single move. Underwriting that is calendar work. Three steps:
Pin your county’s next general reappraisal year. Counties run on different schedules within the eight-year cycle, so this is a county-specific question with a definite answer. Get it from the county assessor or the Department of Revenue’s published schedule rather than assuming, because the entire analysis turns on that date.
Hold taxes flat to that date, then reset to your trade basis. On a five- or seven-year hold, whether that January 1 lands inside or outside your loan term moves debt service coverage and the refinance test materially. A seven-year loan closing two years before a reappraisal takes the step-up in year three and carries it for four more. A seven-year loan closing just after one gets a clean run.
Then test whether the step-up can be pulled forward. Section 105-286 requires a county with a population of 75,000 or more to advance its reappraisal when its sales-assessment ratio falls below .85 or exceeds 1.15, effective no later than the third year following the year the county received notice, or the eighth year after the last reappraisal, whichever is earlier. A county may also advance voluntarily by resolution of the board of commissioners, and may adopt a shorter cycle. In a market where Charlotte has 16,508 units under construction and values have moved hard since the last cycle, the gap between assessed and market value can be large enough to force exactly that advancement. That is the scenario to stress, because it arrives faster than the eight-year schedule suggests.
Three other North Carolina features worth knowing.
The excise tax falls on the deed and the seller pays it. Under N.C.G.S. § 105-228.30 the tax is $1.00 on each $500 of value, or 0.2%, levied on each instrument by which an interest in real property is conveyed, and the transferor must pay the tax to the register of deeds before recording. On a $40 million trade that is $80,000, borne by the seller. The statute addresses instruments conveying an interest in real property, so a deed of trust is a different animal, and recording costs on the loan side here are modest compared with Maryland or Minnesota.
Rent control is preempted, with one exception that matters. N.C.G.S. § 42-14.1 provides that no county or city may enact, maintain or enforce an ordinance regulating the amount of rent charged for privately owned residential or commercial rental property. But localities may regulate rent on property they own, subsidized property under private agreement, property assisted with community development block grant funds, and property receiving local funding or incentives. An unsubsidized North Carolina deal carries no rent regulation risk. A deal that accepted local incentives can be rent-regulated, and that is a diligence item rather than an assumption.
Foreclosure has an upset bid period that restarts. Under N.C.G.S. § 45-21.27 an upset bid may be filed by the close of business on the tenth day after the report of sale is filed, at not less than 5% above the last bid with a minimum increase of $750, and there may be successive upset bids each of which shall be followed by a period of 10 days for a further upset bid. The sale is not final on the courthouse steps, and the clock resets with each bid. For a lender that is an open-ended disposition timeline and it shapes credit-bid strategy.
2026 North Carolina Multifamily Metro Snapshots
A look at the North Carolina metros we most actively finance, with 2026 market indicators and the local supply and demand picture:
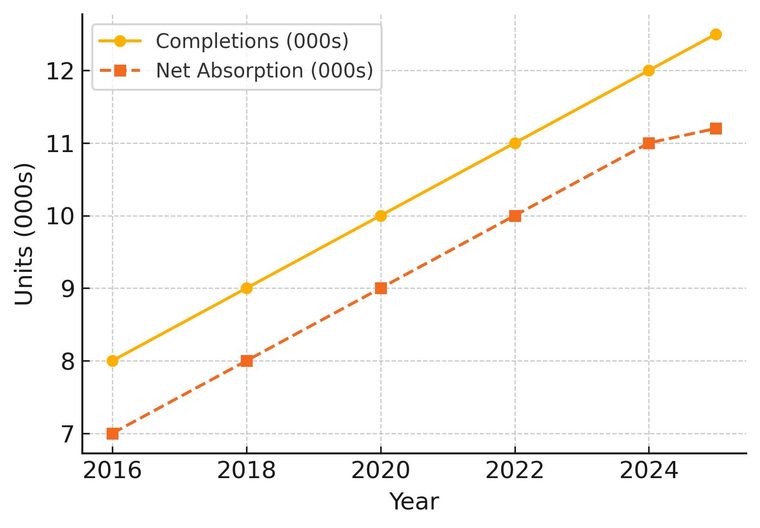
- Employment Growth: Charlotte is projected to add about 14,000 jobs in 2026.
- Construction Trends: Inventory is projected to expand about 3.9%, with roughly 10,000 units referenced in the forecast.
- Vacancy: Vacancy is expected to hold near 5.1%, about 140 bps below the long-term average.
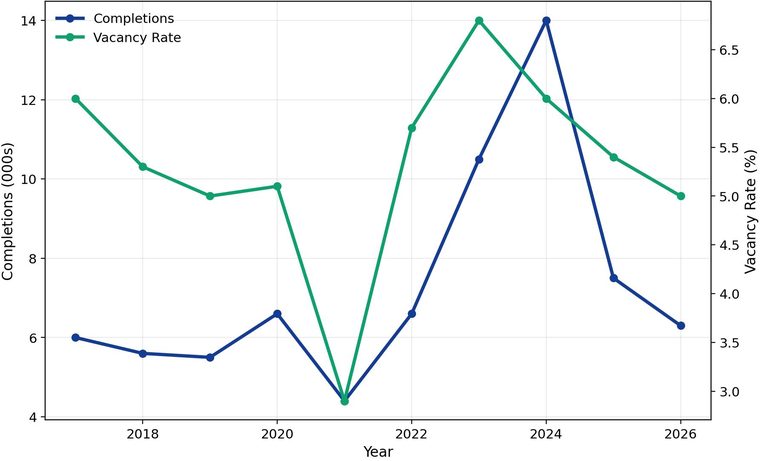
- Employment grows by 9,000 jobs, 10th among major metros.
- Inventory growth slows to 2.9 percent as deliveries ease.
- Vacancy declines to 5.0 percent, the lowest since 2021.
North Carolina Multifamily Loan Programs
As a broker, we compare every large-balance program to find your best fit:
Recent Multifamily Loan Closings
A sample of apartment and multifamily loans we have arranged for investors nationwide.





Other Property & Loan Types We Finance in North Carolina
As a full-service commercial mortgage broker, we arrange North Carolina financing across every major property and loan type:
We consider commercial loan requests of all sizes, beginning at $1,500,000.
What Our Clients Say
“As a real estate attorney, I trust that Select Commercial will deliver commercial mortgages in a timely manner. My clients are always handled professionally, and the rates and terms are excellent. I heartily recommend them.”
David S. · New York City“I spoke to several commercial lenders before finding Select Commercial. They got me a lower rate and their service was exceptional. If you need a multifamily loan, you need to talk to Stephen.”
Nathan B. · Philadelphia, PA“Select Commercial was very helpful with my multifamily mortgage. Stephen went over several options and we came up with the best lender to meet my needs. I got the funds and also lowered my payments.”
Gary M. · Portland, OR“Select Commercial offered 100% financing for my medical practice when my bank would have required 20% down. They delivered something my bank could not, and handled everything professionally.”
John C. · Boston, MAGet Your North Carolina Multifamily Loan Quote
No cost, no obligation. Written answers within 48 hours on North Carolina multifamily loans over $6,000,000.
- No application or processing fees
- Written answers within 48 hours
- For 5+ unit and commercial properties, $1.5M and up