
Indiana · Over $6 Million
Indiana Multifamily Loans
Select Commercial arranges Indiana multifamily loans, with rates as low as 6.22%, up to 80% LTV and non-recourse agency options. We compare Fannie Mae, Freddie Mac, FHA/HUD and CMBS. For loans under $6 million, see Indiana apartment loans. See current rates on every loan type we offer.
Get a Free QuoteFinancing Options in Indiana
Indiana apartment, multifamily and commercial properties each have dedicated financing. Pick the page that matches your property:
Financing more of the state? See Indiana apartment loans and Indiana commercial mortgages.
Financing in another state? Explore our apartment loans, multifamily loans and commercial mortgages nationwide.
Indiana Multifamily Loan Rates
Rates updated as of October 21, 2026
| Loan Type | Rate* | Max LTV |
|---|---|---|
| 5 Year Fixed | 6.22% | Up to 80% |
| 7 Year Fixed | 6.26% | Up to 80% |
| 10 Year Fixed | 6.35% | Up to 80% |
- Streamlined underwriting for institutional multifamily
- Cash-out refinances are acceptable
- Interest-only and non-recourse options
- Minimum 1.25x debt-service-coverage ratio
Indiana Apartment Loans
For smaller apartment building loans, under $6 million
Rates last updated October 21, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
Indiana Apartment Building Loans
Not every Indiana apartment property is over $6 million, and we finance smaller buildings too. For 5+ unit Indiana apartment properties from $1,500,000 to $6 million, see our Indiana apartment loans page for Fannie Mae Small Loan, Freddie Mac SBL, bank and credit union options.
Compare Indiana Large-Balance Programs
As a broker we place your large-balance Indiana multifamily loan with the right capital source. Typical starting points for properties over $6 million:
| Program | Typical rate* | Max leverage | Best for |
|---|---|---|---|
| Fannie Mae DUS | 6.22% | Up to 80% | Non-recourse, fixed to 30 yrs |
| Freddie Mac | 6.26% | Up to 80% | Non-recourse large-balance |
| FHA / HUD | 6.83% | Up to 85% | Highest leverage, 35-yr amortization |
| CMBS / conduit | 7.00% | Up to 75% | Non-recourse, flexible underwriting |
Most large-balance lenders look for a debt-service-coverage ratio (DSCR) of at least 1.25x. For properties under $6 million, see our Indiana apartment loans.
Rates last updated October 21, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
2026 Indiana Multifamily Investment and Lending Outlook
Indianapolis offers one of the better income-to-price ratios among large Midwest metros, and enough transaction volume to support an appraisal.
Kirkland reported Indianapolis multifamily sales of roughly $949 million across 9,475 units in 50 transactions for the twelve months ending February 2026. Berkadia put the average cap rate near 5.9% and the average price near $153,962 per unit.
Fifty transactions in twelve months is the figure that matters most for a borrower. Liquidity is what gives an appraiser a defensible sales comparison conclusion, and it is why Indianapolis files move more predictably than files in states producing a handful of institutional trades a year. A 5.9% cap at roughly $154,000 per door also means Indiana properties clear debt service coverage tests at leverage levels that coastal markets cannot reach at the same rate.
Indiana also has unusually deep local agency capacity. Merchants Capital, headquartered in Carmel, reported more than $7 billion of production in 2025 and is among the larger Fannie Mae, Freddie Mac and HUD lenders in the country. For a stabilized Indiana property, the agency execution is competitive on both rate and term, and the state has lenders who underwrite this market every week rather than occasionally.
Fort Wayne, Evansville and South Bend trade at lower per-unit values with correspondingly higher cap rates. Loan sizes over $6 million in those markets usually mean a large single property or a portfolio.
Indiana’s 2% Cap Is Real, and It Is Not a Ceiling
Indiana gives rental apartments a genuine property tax advantage over most states, and then leaves a door open that borrowers routinely underwrite as if it were closed.
The advantage first. Indiana’s constitutional property tax caps, administered through the circuit breaker credit, limit the tax bill to a percentage of gross assessed value by property type: 1% for homesteads, 2% for other residential and agricultural land, and 3% for other real and personal property. Residential rental property, including apartment buildings, sits in the 2% tier, not the 3% commercial tier. In most states a rental apartment building is taxed as commercial property. In Indiana it is not, and that difference flows straight through to net operating income and therefore to proceeds.
Now the door. Charges approved by voter referendum are exempt from the caps and are added outside them. A referendum operating levy or a school building referendum is billed on top of the capped amount, so the 2% figure is a cap on the base levy rather than a cap on the bill.
There is a live example on the calendar. A four-year operating referendum covering all schools within the Indianapolis Public Schools boundary, district and participating charter, is on the November 2026 ballot at 37.2 cents per $100 of assessed value, or 0.372%. On a Marion County apartment property assessed at $10 million, that is roughly $37,200 per year charged outside the cap. On a $25 million property it is about $93,000.
For a loan closing in the next several weeks, the underwriting approach is straightforward: model both outcomes. Run the tax line with the referendum passing and with it failing, and make sure debt service coverage clears in the first case. If it only clears in the second, you are relying on an election result, and the loan will be sized by whichever number the lender chooses rather than by the one you prefer.
The broader habit is worth keeping beyond this vote. When you pull an Indiana property’s tax history, separate the capped base levy from any referendum charges riding on top, and check the taxing district for referendums already approved and still being collected. The capped portion is predictable. The referendum portion is a political variable with a four-year life, and it belongs in the model as one.
2026 Indiana Multifamily Metro Snapshots
A look at the Indiana metros we most actively finance, with 2026 market indicators and the local supply and demand picture:
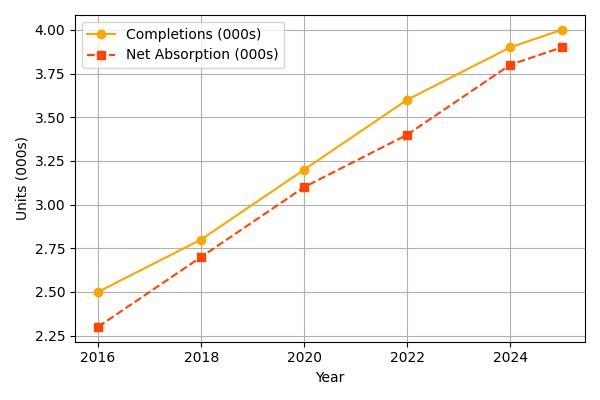
- Employment: about 12,000 new jobs
- Construction: about 2,100 units, inventory growth of 1.1%
- Vacancy: around 4.2% by year-end
Indiana Multifamily Loan Programs
As a broker, we compare every large-balance program to find your best fit:
Recent Multifamily Loan Closings
A sample of apartment and multifamily loans we have arranged for investors nationwide.





Other Property & Loan Types We Finance in Indiana
As a full-service commercial mortgage broker, we arrange Indiana financing across every major property and loan type:
We consider commercial loan requests of all sizes, beginning at $1,500,000.
What Our Clients Say
“As a real estate attorney, I trust that Select Commercial will deliver commercial mortgages in a timely manner. My clients are always handled professionally, and the rates and terms are excellent. I heartily recommend them.”
David S. · New York City“I spoke to several commercial lenders before finding Select Commercial. They got me a lower rate and their service was exceptional. If you need a multifamily loan, you need to talk to Stephen.”
Nathan B. · Philadelphia, PA“Select Commercial was very helpful with my multifamily mortgage. Stephen went over several options and we came up with the best lender to meet my needs. I got the funds and also lowered my payments.”
Gary M. · Portland, OR“Select Commercial offered 100% financing for my medical practice when my bank would have required 20% down. They delivered something my bank could not, and handled everything professionally.”
John C. · Boston, MAGet Your Indiana Multifamily Loan Quote
No cost, no obligation. Written answers within 48 hours on Indiana multifamily loans over $6,000,000.
- No application or processing fees
- Written answers within 48 hours
- For 5+ unit and commercial properties, $1.5M and up