
Kentucky · Over $6 Million
Kentucky Multifamily Loans
Select Commercial arranges Kentucky multifamily loans, with rates as low as 6.14%, up to 80% LTV and non-recourse agency options. We compare Fannie Mae, Freddie Mac, FHA/HUD and CMBS. For loans under $6 million, see Kentucky apartment loans. See current rates on every loan type we offer.
Get a Free QuoteFinancing Options in Kentucky
Kentucky apartment, multifamily and commercial properties each have dedicated financing. Pick the page that matches your property:
Financing more of the state? See Kentucky apartment loans and Kentucky commercial mortgages.
Financing in another state? Explore our apartment loans, multifamily loans and commercial mortgages nationwide.
Kentucky Multifamily Loan Rates
Rates updated as of October 22, 2026
| Loan Type | Rate* | Max LTV |
|---|---|---|
| 5 Year Fixed | 6.14% | Up to 80% |
| 7 Year Fixed | 6.17% | Up to 80% |
| 10 Year Fixed | 6.21% | Up to 80% |
- Streamlined underwriting for institutional multifamily
- Cash-out refinances are acceptable
- Interest-only and non-recourse options
- Minimum 1.25x debt-service-coverage ratio
Kentucky Apartment Loans
For smaller apartment building loans, under $6 million
Rates last updated October 22, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
Kentucky Apartment Building Loans
Not every Kentucky apartment property is over $6 million, and we finance smaller buildings too. For 5+ unit Kentucky apartment properties from $1,500,000 to $6 million, see our Kentucky apartment loans page for Fannie Mae Small Loan, Freddie Mac SBL, bank and credit union options.
Compare Kentucky Large-Balance Programs
As a broker we place your large-balance Kentucky multifamily loan with the right capital source. Typical starting points for properties over $6 million:
| Program | Typical rate* | Max leverage | Best for |
|---|---|---|---|
| Fannie Mae DUS | 6.14% | Up to 80% | Non-recourse, fixed to 30 yrs |
| Freddie Mac | 6.17% | Up to 80% | Non-recourse large-balance |
| FHA / HUD | 6.74% | Up to 85% | Highest leverage, 35-yr amortization |
| CMBS / conduit | 7.03% | Up to 75% | Non-recourse, flexible underwriting |
Most large-balance lenders look for a debt-service-coverage ratio (DSCR) of at least 1.25x. For properties under $6 million, see our Kentucky apartment loans.
Rates last updated October 22, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
2026 Kentucky Multifamily Investment and Lending Outlook
Kentucky’s two large-balance markets are at opposite points of the supply cycle, and Lexington is the one that needs watching.
In Louisville, Cushman & Wakefield’s Commercial Kentucky multifamily team reported rent growth of 0% year over year for the first quarter of 2026, with 3,995 units delivered over the trailing twelve months, 3,524 units under construction and more than 14,200 units planned. Metro employment was down 1.6% year over year and unemployment had risen to 4.6% from 4.0% two quarters earlier. Recent Class B trades priced in a band that frames the market: La Fontenay at 248 units and roughly $131,000 per unit, and The Heritage by Fairlawn at 163 units and roughly $155,000 per unit. Note that this publisher’s Louisville figures include the Southern Indiana submarkets, so they will not match data cut to the Kentucky side alone.
Lexington looks healthier today and carries more forward risk. As of the second quarter of 2026 the same publisher reported average occupancy of 94.9%, down 30 basis points from year-end 2025, with an average rental rate of $1,343 per month, up 2.0% from $1,317 a year earlier. Year-to-date 2026 sales totaled $72,787,500 across 649 units, about $112,153 per unit.
Here is the number that matters. Lexington units under construction went from 1,068 in mid-2025 to 2,503 in mid-2026, an increase of roughly 134%, while only 101 units actually delivered in that twelve-month span. That is a supply wave that has been permitted and started but has not yet landed. Any Lexington underwriting that extends a 2% rent growth assumption through 2027 and 2028 is assuming those 2,503 units absorb without concessions. Submarket matters: the North submarket leads under construction with about 1,300 units.
Both publishers chart Kentucky cap rates without printing a figure, so we do not quote one. Ask for current comparable sales on your specific submarket instead.
Kentucky Writes the Cap-Rate Formula Into Statute, for Rent-Restricted Apartments
Kentucky does something almost no other state does: it writes the capitalization rate used to assess income-restricted apartment property into the statute, and then has the Department of Revenue publish the exact range every year. For a qualifying property that turns the property tax line from an assumption into a calculation.
KRS 132.191(5), added by House Bill 360 and effective March 24, 2023, directs that multi-unit rental housing subject to government restriction on use may be valued through an annual net operating income approach to value that uses actual income and stabilized operating expenses, with methodology consistent with the Uniform Standards of Professional Appraisal Practice. The capitalization rate must reflect the risks of government-restricted housing including diminished ownership control, must be equal to or greater than the rate used for unrestricted multi-unit rental housing, and must fall in the range of 50 to 150 basis points above the most recent quarterly survey of national average multifamily cap rates published by RealtyRates.com.
The published tax year 2026 range: an unloaded cap rate of 9.10% to 10.10%, and a loaded cap rate including an example effective tax rate of 10.25% to 11.25%. The derivation is printed with it: the fourth quarter 2025 RealtyRates national average of 8.60%, plus the statutory 50 to 150 basis point adjustment.
Three consequences follow, and they are unusually concrete.
You can compute next year’s assessment from this year’s operating statement. Net operating income divided by the published loaded cap rate gives the assessed value, and the local millage gives the tax. On most deals in most states the out-year tax line is the largest single source of net operating income uncertainty. On a qualifying Kentucky property it is arithmetic, and that tightens the sizing in the borrower’s favor rather than against it.
Low-income housing tax credits are statutorily excluded from value. KRS 132.191(5)(b) provides that income tax credits received under Section 42 of the Internal Revenue Code, or from any state or federal program, shall not be included in the valuation. Assessors previously argued credit value onto the roll, and that argument is now foreclosed. For a lender underwriting across a fifteen-year compliance period, that removes a recurring dispute from the out-year projection.
The governing number changes every year, so timing matters. The range is recomputed annually off the prior fourth quarter survey and is not knowable until Revenue posts it. A deal underwritten mid-year on last year’s range is underwritten on a stale rate. Pull the current publication at application and again at rate lock, and keep a copy, because the Department replaces the page at the same address each year.
Where this does not reach: KRS 132.191(5) is a government-restricted-property rule. A conventional market-rate Kentucky apartment building gets no benefit from it and is valued the ordinary way. Whether a particular property qualifies turns on its restriction documents and the share of units held at or below the applicable area median income threshold, so confirm it against the property’s own regulatory agreement rather than assuming.
2026 Kentucky Multifamily Metro Snapshots
A look at the Kentucky metros we most actively finance, with 2026 market indicators and the local supply and demand picture:
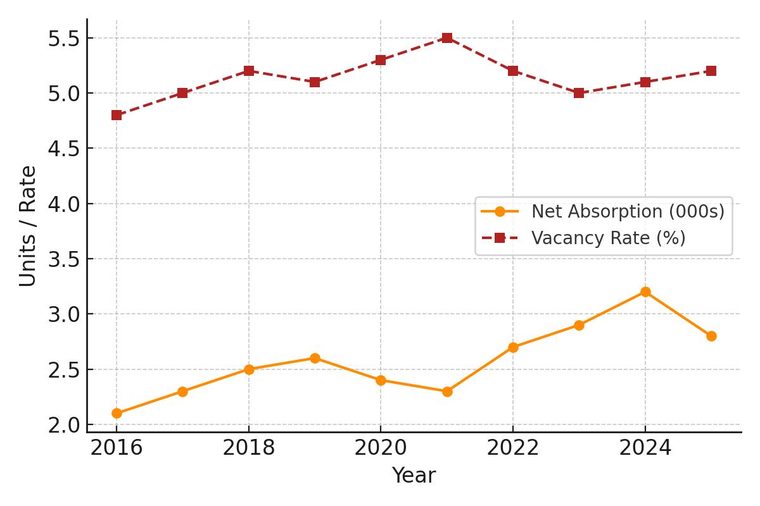
- Employers add about 7,500 jobs, a top-five job growth rate nationally.
- Deliveries halve from 2025, holding inventory growth to 1.0 percent.
- Vacancy edges up to 4.5 percent, still 150 basis points below average.
Kentucky Multifamily Loan Programs
As a broker, we compare every large-balance program to find your best fit:
Recent Multifamily Loan Closings
A sample of apartment and multifamily loans we have arranged for investors nationwide.





Other Property & Loan Types We Finance in Kentucky
As a full-service commercial mortgage broker, we arrange Kentucky financing across every major property and loan type:
We consider commercial loan requests of all sizes, beginning at $1,500,000.
What Our Clients Say
“As a real estate attorney, I trust that Select Commercial will deliver commercial mortgages in a timely manner. My clients are always handled professionally, and the rates and terms are excellent. I heartily recommend them.”
David S. · New York City“I spoke to several commercial lenders before finding Select Commercial. They got me a lower rate and their service was exceptional. If you need a multifamily loan, you need to talk to Stephen.”
Nathan B. · Philadelphia, PA“Select Commercial was very helpful with my multifamily mortgage. Stephen went over several options and we came up with the best lender to meet my needs. I got the funds and also lowered my payments.”
Gary M. · Portland, OR“Select Commercial offered 100% financing for my medical practice when my bank would have required 20% down. They delivered something my bank could not, and handled everything professionally.”
John C. · Boston, MAGet Your Kentucky Multifamily Loan Quote
No cost, no obligation. Written answers within 48 hours on Kentucky multifamily loans over $6,000,000.
- No application or processing fees
- Written answers within 48 hours
- For 5+ unit and commercial properties, $1.5M and up