
Dallas, Texas
Dallas Apartment Loans in 2026
Select Commercial arranges financing for apartment buildings of five or more units in Dallas and across North Texas, from $1,500,000, with rates as low as 6.32% and up to 80% LTV. We are a broker, so we compare agency, bank, FHA and bridge programs and place your loan where it prices best. For buildings elsewhere in the state, see how apartment financing works across Texas. For larger properties we offer lower rates: see our best rates on properties over $6,000,000. Pricing for every program is on our commercial mortgage rates page.
Get a Free QuoteApartment Loan Rates
Rates updated as of November 18, 2026
| Loan Type | Rate* | Max LTV |
|---|---|---|
| 5 Year Fixed | 6.52% | Up to 80% |
| 7 Year Fixed | 6.55% | Up to 80% |
| 10 Year Fixed | 6.59% | Up to 80% |
- Cash-out refinances are acceptable
- Interest-only and non-recourse options
- Minimum 1.25x debt-service-coverage ratio
See Rates for Larger Properties, Starting at 6.32%
Rates last updated November 18, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
How to Qualify for the Best Rate
The rates in the table are best-case pricing. In North Texas right now, how close you come to them depends largely on how your building came through the recent wave of new construction.
- Show occupancy that held. Deliveries across the metroplex are falling to less than half of the 2025 level, but a lot of new units opened first. A rent roll that stayed full while new buildings leased up nearby is the strongest thing you can put in front of a lender.
- Be upfront about concessions. Concessions are still common here, most of all in Class C. A concession shows up in effective rent but not on the rent roll, and the gap between the two is the first thing an underwriter checks. Give us the real numbers and the loan gets sized correctly the first time.
- Borrow a little less. With many rates in the 6% to 7% range, loans often size to 65% to 70% of value. A request in that range prices better and is more likely to pass the coverage test.
- Let the programs compete. The same building can price differently at an agency lender, a bank and a credit union. Running that comparison is what a broker is for.
Which Page Fits Your Property?
We keep separate pages by loan size and property type, because the lenders and the pricing are different for each:
Financing in another state? Explore our apartment loans, multifamily loans and commercial mortgages nationwide.
Compare Loan Programs
We price your building against every program below and tell you which one fits. Typical starting points:
| Program | Typical rate* | Max leverage | Best for |
|---|---|---|---|
| Fannie Mae Small Loan | 6.52% | Up to 80% | Non-recourse, fixed to 30 yrs |
| Freddie Mac SBL | 6.55% | Up to 80% | $2M to $10M small balance |
| FHA / HUD | 6.74% | Up to 85% | Highest leverage, longest term |
| Bank / portfolio | 6.75% | Up to 75% | Flexible, value-add |
| Bridge | 9.50% | Up to 80% LTC | Reposition, lease-up |
Most lenders look for a debt-service-coverage ratio (DSCR) of at least 1.25x. Larger loans are usually a better fit for the agency and CMBS programs on our multifamily page.
Rates last updated November 18, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
Can I Qualify?
Usually yes, if the building carries itself. In Dallas the question is less about the price of the property and more about its income. With average rents near $1,540 a month and vacancy heading toward 5.9%, a lender wants to see net operating income that covers the loan payment at least 1.25 times after concessions are counted.
- Where the building sits. Submarkets that took the most new supply, such as Allen-McKinney and Frisco, get a closer look at rents and lease-up competition. Mid-tier properties are in the best position after the recent improvement in vacancy.
- Occupancy and condition. Stabilized buildings in sound condition get the best terms. A property in lease-up or mid-renovation usually starts with a bank or bridge loan and moves to permanent financing later.
- You as the borrower. Experience with similar properties, credit, net worth and cash on hand after closing.
- Size. Five or more units and a loan of at least $1,500,000.
To get a firm answer quickly, send a current rent roll, the trailing twelve months of income and expenses, a personal financial statement and, for a purchase, the contract.
The Dallas Market in 2026: Supply Cools as Demand Catches Up
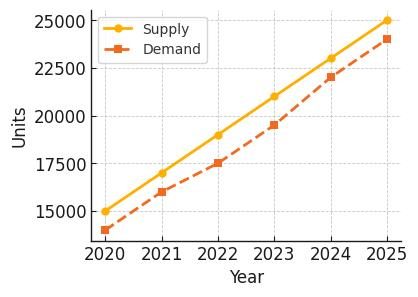
After several years of heavy construction, the metroplex is working through its new supply. Deliveries in 2026 are expected to fall to less than half of the 2025 level, and inventory growth should moderate to about 2.1%. The areas that took the most new units, such as Allen-McKinney and Frisco, are also where office and retail development is adding jobs.
Demand is holding up. Hiring is slower than the long-term average, but Dallas-Fort Worth is still projected to add about 25,000 jobs this year, tying for the largest total gain in the country, helped by population growth and corporate relocations. Vacancy is forecast to move down to about 5.9% by year-end, roughly 30 basis points below the long-term average, and rents to rise about 1.8% to an average near $1,540 a month.

What this means for your financing
Lenders underwrite to the income a building collects today, so the direction of vacancy and concessions matters more than the headline rent. Mid-tier properties are in the best position after the recent improvement in vacancy, while concessions remain more common in Class C. If your building sits in a submarket that absorbed a lot of new supply, expect the underwriter to compare effective rents with the rent roll. Steady occupancy through the supply wave is a strong point, and we put it at the front of the loan request.
Financing Larger Properties
Above $6 million we arrange financing through Fannie Mae DUS, Freddie Mac, FHA/HUD and CMBS. These institutional programs offer non-recourse terms, up to 80% LTV and fixed periods up to 30 years, with longer fully amortizing options through HUD.
Details and current pricing are on our page for larger multifamily properties, or go straight to the Fannie Mae and Freddie Mac program pages.
Recent Closings
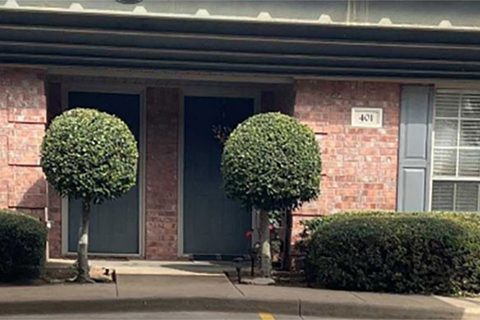
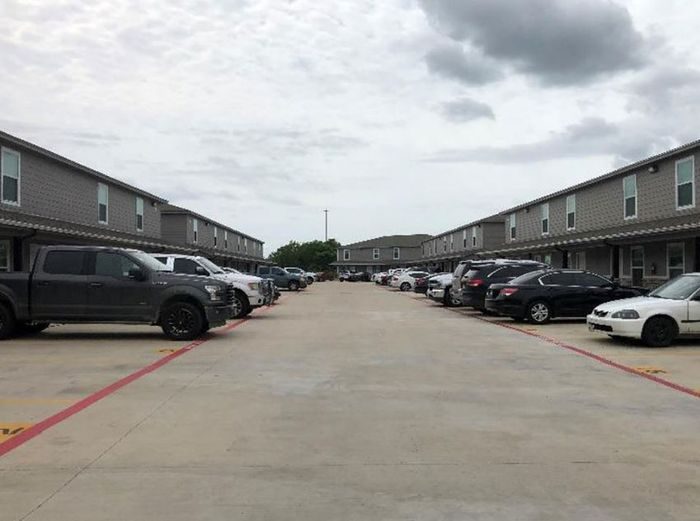
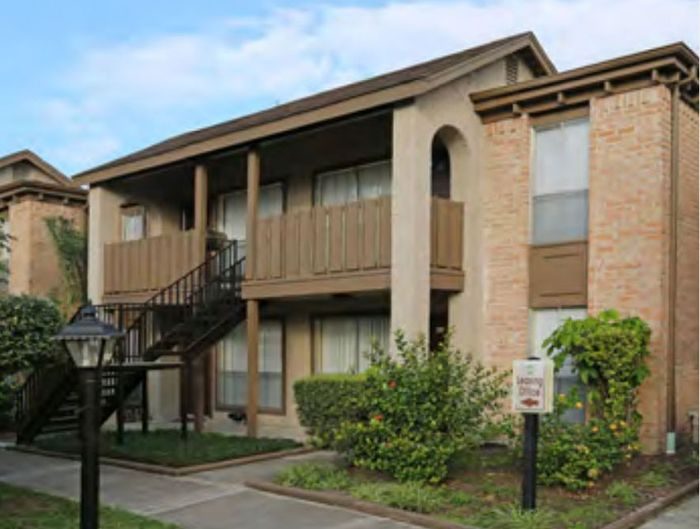
A sample of the financing we have arranged for apartment investors, Texas deals first.
Other Property Types We Finance
As a full-service commercial mortgage broker, we also arrange financing across every major property type:
We consider commercial loan requests of all sizes, beginning at $1,500,000.
Nearby Markets
We finance apartment buildings nationwide. Related markets:
Houston · Austin · San Antonio · El Paso · Lubbock · Plano · Arlington · Fort Worth · All Texas · Other U.S. cities
What Our Clients Say
“I am a veterinarian who purchased an existing practice. I was surprised to find a company that offered 100% financing at a good rate, with great terms and rates for medical office financing.”
Carol K. · Chicago, IL“I spoke to several commercial lenders before finding Select Commercial. They got me a lower rate and their service was exceptional. If you need a multifamily loan, you need to talk to Stephen.”
Nathan B. · Philadelphia, PA“Select Commercial was very helpful with my multifamily mortgage. Stephen went over several options and we came up with the best lender to meet my needs. I got the funds and also lowered my payments.”
Gary M. · Portland, OR“Select Commercial offered 100% financing for my medical practice when my bank would have required 20% down. They delivered something my bank could not, and handled everything professionally.”
John C. · Boston, MAGet a Quote on Your Building
No cost, no obligation. Written answers within 48 hours on loans from $1,500,000.
- No application or processing fees
- Written answers within 48 hours
- For 5+ unit and commercial properties, $1.5M and up