
Florida · Over $6 Million
Florida Multifamily Loans
Select Commercial arranges Florida multifamily loans, with rates as low as 6.14%, up to 80% LTV and non-recourse agency options. We compare Fannie Mae, Freddie Mac, FHA/HUD and CMBS. For loans under $6 million, see Florida apartment loans. See current rates on every loan type we offer.
Get a Free QuoteFinancing Options in Florida
Florida apartment, multifamily and commercial properties each have dedicated financing. Pick the page that matches your property:
Financing more of the state? See Florida apartment loans and Florida commercial mortgages.
Financing in another state? Explore our apartment loans, multifamily loans and commercial mortgages nationwide.
Florida Multifamily Loan Rates
Rates updated as of October 22, 2026
| Loan Type | Rate* | Max LTV |
|---|---|---|
| 5 Year Fixed | 6.14% | Up to 80% |
| 7 Year Fixed | 6.17% | Up to 80% |
| 10 Year Fixed | 6.21% | Up to 80% |
- Streamlined underwriting for institutional multifamily
- Cash-out refinances are acceptable
- Interest-only and non-recourse options
- Minimum 1.25x debt-service-coverage ratio
Florida Apartment Loans
For smaller apartment building loans, under $6 million
Rates last updated October 22, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
Florida Apartment Building Loans
Not every Florida apartment property is over $6 million, and we finance smaller buildings too. For 5+ unit Florida apartment properties from $1,500,000 to $6 million, see our Florida apartment loans page for Fannie Mae Small Loan, Freddie Mac SBL, bank and credit union options.
Compare Florida Large-Balance Programs
As a broker we place your large-balance Florida multifamily loan with the right capital source. Typical starting points for properties over $6 million:
| Program | Typical rate* | Max leverage | Best for |
|---|---|---|---|
| Fannie Mae DUS | 6.14% | Up to 80% | Non-recourse, fixed to 30 yrs |
| Freddie Mac | 6.17% | Up to 80% | Non-recourse large-balance |
| FHA / HUD | 6.74% | Up to 85% | Highest leverage, 35-yr amortization |
| CMBS / conduit | 7.03% | Up to 75% | Non-recourse, flexible underwriting |
Most large-balance lenders look for a debt-service-coverage ratio (DSCR) of at least 1.25x. For properties under $6 million, see our Florida apartment loans.
Rates last updated October 22, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
2026 Florida Multifamily Investment and Lending Outlook
Florida’s larger multifamily markets are no longer moving together, and the ranking has changed.
Jacksonville recorded trailing-twelve-month volume of roughly $1.15 billion, up 25.6%, at an average cap rate near 5.57% and about $153,000 per unit. Miami posted about $894 million from January through April 2026. Tampa recorded roughly $386 million, and Orlando about $347 million at roughly $174,502 per unit.
Jacksonville leading on both volume and growth is the headline, with the caveat that its figure covers a full twelve months while the Miami, Tampa and Orlando figures cover shorter 2026 windows and are not directly comparable. It is the cheapest per door of the markets with a published figure and the only one posting a sharp increase, which tells you where the yield buyers went when South Florida pricing stopped working for leveraged capital.
Two statewide expense items are doing more to Florida valuations than rent growth is. Property insurance remains the single largest swing factor in a Florida pro forma, and an insurance quote that is twelve months old is not usable for underwriting. Property tax reassessment on sale is the second: Florida reassesses to the purchase price, so a buyer’s tax bill frequently has little relationship to the seller’s trailing figure. A Florida loan sized on a seller’s operating statement without both lines restated will not survive underwriting, and the borrower who restates them first negotiates from a stronger position.
Agency execution remains the primary source for stabilized Florida product at larger balances, with life companies competitive on the strongest assets and banks and debt funds taking the transitional business.
The Live Local Exemption Is a Large-Property Program With a Hard Annual Deadline
Florida’s most consequential multifamily tax provision is structurally available only to larger properties, and it has to be won again every single year.
The Live Local Act created an ad valorem exemption at Florida Statutes § 196.1978(3), generally called the Multifamily Middle Market or Missing Middle exemption. To qualify, a development must contain at least 71 units serving households at or below 120% of area median income, and must be newly constructed within the five years before the owner’s first certification filing. Units serving households at or below 80% of AMI are exempt from 100% of assessed value. Units serving 81% to 120% of AMI are exempt from 75%.
The 71-unit floor is the part that matters for sizing. A 71-unit newly built Florida property is not a small loan, so this exemption is by design a benefit that attaches to larger-balance financing rather than to smaller properties.
The annual cycle is unforgiving, and the next one is about to open. For the 2027 tax year, Florida Housing’s certification portal opens October 15, 2026, which is days away. Qualifying units must have eligible tenants and compliant rents in place by January 1, 2027. All certification requests and supporting documentation must be submitted through the portal no later than 3:00 p.m. Eastern on January 15, 2027. Receiving the exemption in one year does not carry it into the next. Owners must reapply every year, and Florida Housing’s certification notice is not the final word: the county property appraiser makes the determination.
That structure dictates how a lender treats it. Because the benefit is annual, conditional and administered by two separate authorities, most underwriters will not capitalize it as a permanent expense reduction. Expect the tax line to be underwritten at the unexempted figure, or at a substantial haircut, with the exemption treated as upside to equity rather than as debt capacity. A borrower who presents the exemption as a given, and whose debt service coverage only works with it, is presenting a file that will be resized.
The right approach is to underwrite the deal without the exemption, show the lender it works, and then show what the exemption adds. If your property qualifies, document the certification history and the compliance monitoring, because a lender that can see three consecutive approved years will give the benefit more credit than one looking at a first application.
2026 Florida Multifamily Metro Snapshots
A look at the Florida metros we most actively finance, with 2026 market indicators and the local supply and demand picture:
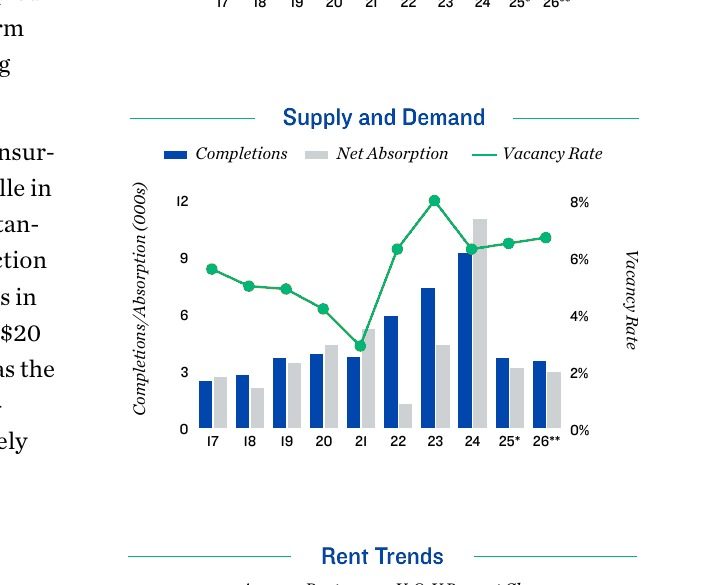
- Employment grows by 6,000 jobs, up roughly 0.7 percent for 2026.
- Inventory expands 2.3 percent, the sixth-fastest pace among major U.S. markets.
- Vacancy climbs to 6.7 percent, second highest among major rental markets.
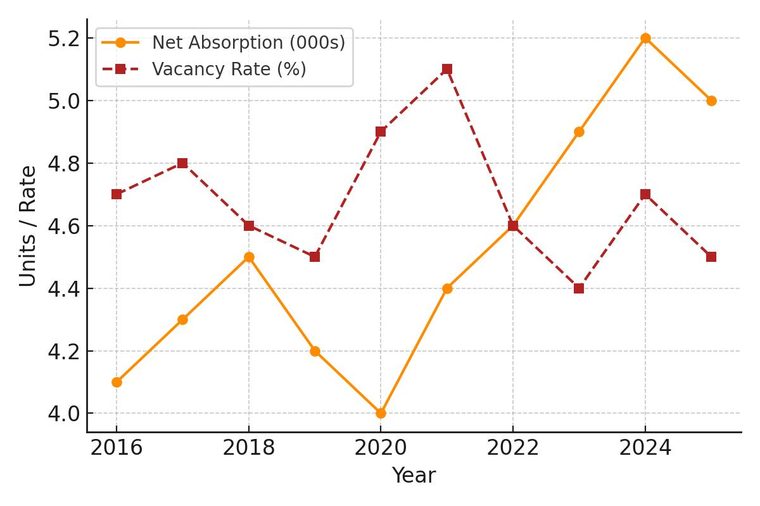
- Employment: Miami-Dade adds about 9,000 jobs in 2026 (about +0.7%)
- Construction: about 5,500 units projected, inventory growth around 1.6%
- Vacancy: forecast near 4.9% (about +20 bps)
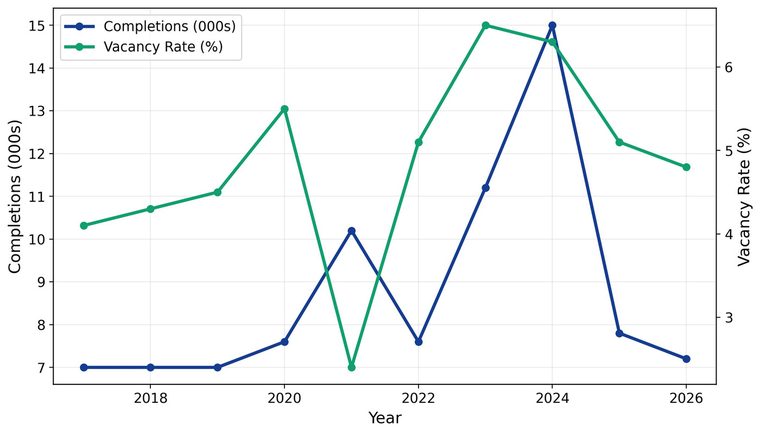
- Employment Growth: About 8,500 jobs added in 2026 (approximately +0.6%).
- Construction Trends: About 7,000 units projected for delivery, with inventory growth near 2.4%.
- Vacancy: Vacancy projected near 4.8%, improving by roughly 30 bps.
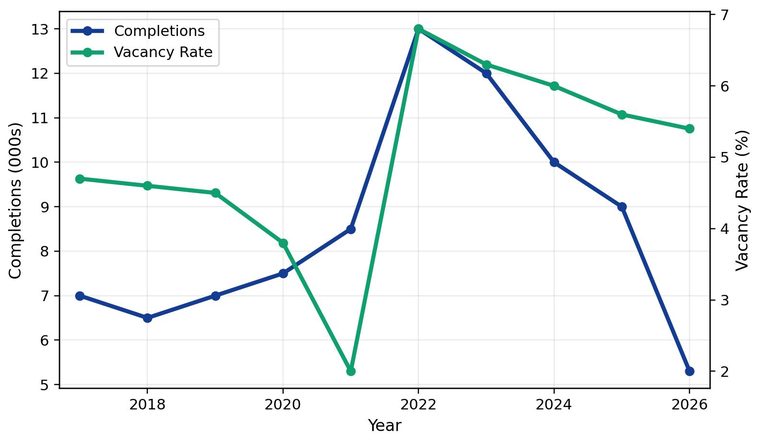
- Employment Growth: About 6,000 jobs added in 2026 (approximately +0.4%) across the Tampa-St. Petersburg market.
- Construction Trends: About 5,300 units projected for delivery in 2026, the lowest level since 2020.
- Vacancy: Vacancy projected near 5.4%, improving by roughly 20 bps.
Florida Multifamily Loan Programs
As a broker, we compare every large-balance program to find your best fit:
Recent Multifamily Loan Closings
A sample of apartment and multifamily loans we have arranged for investors nationwide.





Other Property & Loan Types We Finance in Florida
As a full-service commercial mortgage broker, we arrange Florida financing across every major property and loan type:
We consider commercial loan requests of all sizes, beginning at $1,500,000.
What Our Clients Say
“As a real estate attorney, I trust that Select Commercial will deliver commercial mortgages in a timely manner. My clients are always handled professionally, and the rates and terms are excellent. I heartily recommend them.”
David S. · New York City“I spoke to several commercial lenders before finding Select Commercial. They got me a lower rate and their service was exceptional. If you need a multifamily loan, you need to talk to Stephen.”
Nathan B. · Philadelphia, PA“Select Commercial was very helpful with my multifamily mortgage. Stephen went over several options and we came up with the best lender to meet my needs. I got the funds and also lowered my payments.”
Gary M. · Portland, OR“Select Commercial offered 100% financing for my medical practice when my bank would have required 20% down. They delivered something my bank could not, and handled everything professionally.”
John C. · Boston, MAGet Your Florida Multifamily Loan Quote
No cost, no obligation. Written answers within 48 hours on Florida multifamily loans over $6,000,000.
- No application or processing fees
- Written answers within 48 hours
- For 5+ unit and commercial properties, $1.5M and up