
Georgia · Over $6 Million
Georgia Multifamily Loans
Select Commercial arranges Georgia multifamily loans, with rates as low as 6.22%, up to 80% LTV and non-recourse agency options. We compare Fannie Mae, Freddie Mac, FHA/HUD and CMBS. For loans under $6 million, see Georgia apartment loans. See current rates on every loan type we offer.
Get a Free QuoteFinancing Options in Georgia
Georgia apartment, multifamily and commercial properties each have dedicated financing. Pick the page that matches your property:
Financing more of the state? See Georgia apartment loans and Georgia commercial mortgages.
Financing in another state? Explore our apartment loans, multifamily loans and commercial mortgages nationwide.
Georgia Multifamily Loan Rates
Rates updated as of October 21, 2026
| Loan Type | Rate* | Max LTV |
|---|---|---|
| 5 Year Fixed | 6.22% | Up to 80% |
| 7 Year Fixed | 6.26% | Up to 80% |
| 10 Year Fixed | 6.35% | Up to 80% |
- Streamlined underwriting for institutional multifamily
- Cash-out refinances are acceptable
- Interest-only and non-recourse options
- Minimum 1.25x debt-service-coverage ratio
Georgia Apartment Loans
For smaller apartment building loans, under $6 million
Rates last updated October 21, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
Georgia Apartment Building Loans
Not every Georgia apartment property is over $6 million, and we finance smaller buildings too. For 5+ unit Georgia apartment properties from $1,500,000 to $6 million, see our Georgia apartment loans page for Fannie Mae Small Loan, Freddie Mac SBL, bank and credit union options.
Compare Georgia Large-Balance Programs
As a broker we place your large-balance Georgia multifamily loan with the right capital source. Typical starting points for properties over $6 million:
| Program | Typical rate* | Max leverage | Best for |
|---|---|---|---|
| Fannie Mae DUS | 6.22% | Up to 80% | Non-recourse, fixed to 30 yrs |
| Freddie Mac | 6.26% | Up to 80% | Non-recourse large-balance |
| FHA / HUD | 6.83% | Up to 85% | Highest leverage, 35-yr amortization |
| CMBS / conduit | 7.00% | Up to 75% | Non-recourse, flexible underwriting |
Most large-balance lenders look for a debt-service-coverage ratio (DSCR) of at least 1.25x. For properties under $6 million, see our Georgia apartment loans.
Rates last updated October 21, 2026. Rates and maximum LTV shown represent our best-case pricing scenarios. Actual rates, LTV, and loan terms are subject to underwriting approval and may vary.
2026 Georgia Multifamily Investment and Lending Outlook
The supply wave that held Atlanta rents down is finished, and the construction data says so clearly.
Matthews reported Atlanta trailing-twelve-month multifamily volume of roughly $7.3 billion through the second quarter of 2026, up 11.2%, at an average cap rate near 5.59% and about $188,685 per unit. Vacancy held near 5.9%.
The number worth sitting with is the pipeline. Completions over the trailing twelve months ran about 11,842 units, down 47% from the prior period. Units under construction stood near 16,243, equal to 2.71% of existing inventory, against a cycle peak of 8.37%. Atlanta’s pipeline has fallen to roughly a third of its peak share.
That changes what a 2026 Atlanta loan is being underwritten against. For the past three years the open question on any Atlanta file was how much more supply was coming into the submarket during the lease-up or hold period. The pipeline has largely answered it. Deliveries through 2027 are substantially pre-committed and visible, which makes a forward rent assumption easier to defend than it has been since 2021.
It also means the rent trough is becoming a measurable event rather than a forecast. A property that held occupancy through the delivery wave has demonstrated something, and lenders are giving credit for it. One with concession-driven occupancy will be sized on effective rent.
Savannah, Augusta and the Columbus market run on separate drivers, with Savannah in particular tied to port and manufacturing employment rather than to Atlanta’s office-adjacent demand. Treat them as distinct underwriting conversations.
When a Georgia Development Authority Owns Your Building
Georgia has a widely used property tax abatement structure that changes what a lender is actually taking a lien on. If your property has one, it needs to be on the table in the first conversation, not discovered in title review.
Under O.C.G.A. Title 36, Chapter 62, a local development authority may acquire a project, issue taxable revenue bonds to finance it, and lease it back to the developer. Section 36-62-3 provides the authority’s tax exemption. Section 36-62-7 bars the authority from operating the project and requires that it be sold or leased. Sections 36-62-8 and 36-62-9 govern issuance and judicial validation of the bonds.
Mechanically, the authority takes fee title and the developer holds a leasehold. Because the authority’s fee interest is exempt, only the leasehold is taxable, and the taxable value of that leasehold is set by a schedule that starts well below full fee value and escalates annually across the term, commonly ten years. Individual authorities set their own schedules, so the specific percentages are a document question rather than a statewide rule. Verify the schedule in your lease, not from a summary.
For financing, three consequences follow and none of them are optional.
Your collateral is a leasehold estate. The loan is a leasehold mortgage, which means the lender underwrites the lease as carefully as the property: remaining term against loan term, the purchase option, default and cure rights, and whether the lender can step into the lease. A leasehold whose term does not extend meaningfully beyond loan maturity will not support a ten-year fixed-rate loan.
The authority has to participate in your closing. Expect to need its consent to the leasehold mortgage, an estoppel certificate, and in many cases a recognition agreement giving the lender direct rights. Authorities meet on their own calendars. A board that sits monthly can add four to six weeks to a closing timeline, and a rate lock will not wait for the next meeting.
The abatement is finite and scheduled. The tax line rises every year by design. Underwriting the current year’s abated taxes across a ten-year term overstates coverage in every year but the first. Use the stabilized post-abatement figure, or at minimum the figure at loan maturity, and you will be looking at the same number your lender uses.
Bond-lease deals finance well. They just need the lease, the authority and the abatement schedule in hand before anyone quotes a rate.
2026 Georgia Multifamily Metro Snapshots
A look at the Georgia metros we most actively finance, with 2026 market indicators and the local supply and demand picture:
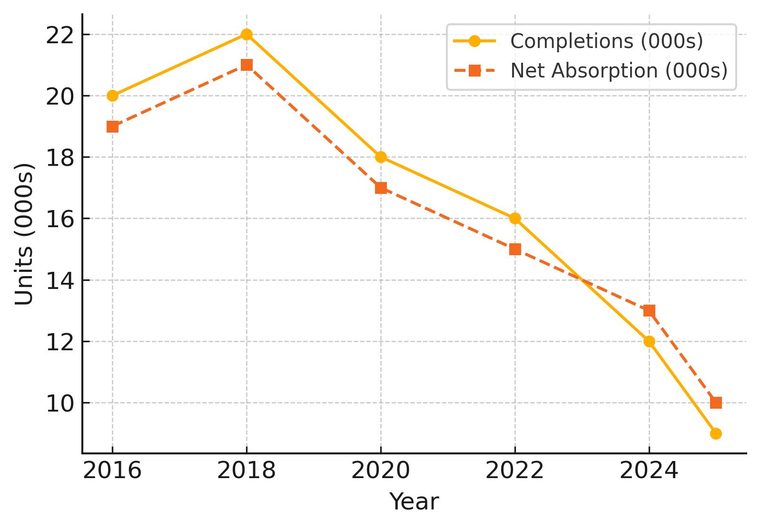
- Employment: about 19,000 new jobs, with office-using employment up about 4,500
- Construction: completions fall sharply versus 2025, inventory growth around 1.4%
- Vacancy: tightens to about 5.2% as in-migration continues and fewer units deliver
Georgia Multifamily Loan Programs
As a broker, we compare every large-balance program to find your best fit:
Recent Multifamily Loan Closings
A sample of apartment and multifamily loans we have arranged for investors nationwide.





Other Property & Loan Types We Finance in Georgia
As a full-service commercial mortgage broker, we arrange Georgia financing across every major property and loan type:
We consider commercial loan requests of all sizes, beginning at $1,500,000.
What Our Clients Say
“As a real estate attorney, I trust that Select Commercial will deliver commercial mortgages in a timely manner. My clients are always handled professionally, and the rates and terms are excellent. I heartily recommend them.”
David S. · New York City“I spoke to several commercial lenders before finding Select Commercial. They got me a lower rate and their service was exceptional. If you need a multifamily loan, you need to talk to Stephen.”
Nathan B. · Philadelphia, PA“Select Commercial was very helpful with my multifamily mortgage. Stephen went over several options and we came up with the best lender to meet my needs. I got the funds and also lowered my payments.”
Gary M. · Portland, OR“Select Commercial offered 100% financing for my medical practice when my bank would have required 20% down. They delivered something my bank could not, and handled everything professionally.”
John C. · Boston, MAGet Your Georgia Multifamily Loan Quote
No cost, no obligation. Written answers within 48 hours on Georgia multifamily loans over $6,000,000.
- No application or processing fees
- Written answers within 48 hours
- For 5+ unit and commercial properties, $1.5M and up